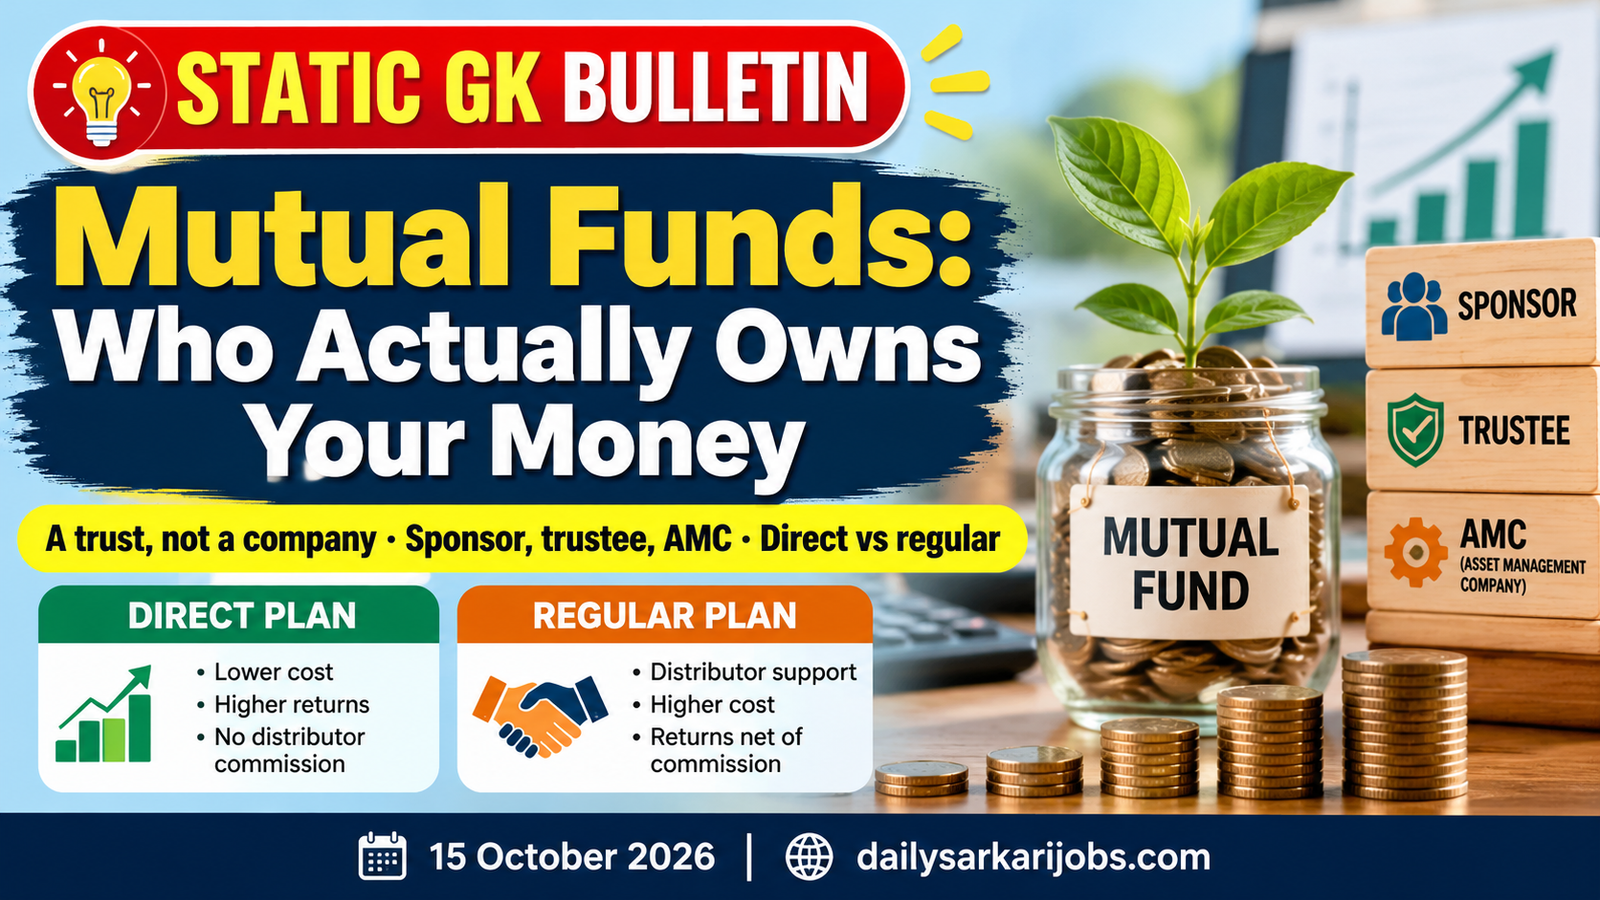
When you put money into a mutual fund, the company whose name is on the fund does not own that money and never will. It cannot be seized if that company fails, because it was never the company’s to begin with. A mutual fund in India is a trust, and everything else about how they are regulated follows from that one legal choice.
This is the second capsule in our series on markets and institutions, explained in plain language for SSC, RRB NTPC, banking exams, State PSC and UPSC Prelims.
⚡ QUICK FACTS
Regulated by
SEBI
The rules in force
SEBI (Mutual Funds) Regulations, 2026, from 1 April 2026
Legal form
A trust — the deed registered under the Registration Act, 1908
Who holds the assets
The trustees, for the unitholders
Who manages the money
The Asset Management Company, or AMC
Minimum AMC net worth
₹50 crore on the ordinary route
Industry body
AMFI — a body of the industry, not a regulator
The Hinge: the Manager Is Not the Owner
Most people picture a mutual fund as a company that takes your money and invests it. That is not the structure, and the difference is the protection.
Tier
Who it is
What it does
Sponsor
The promoter who sets the fund up
Creates the trust and must contribute at least 40 per cent of the AMC’s net worth
Trustees
A trustee company or board of trustees
Hold the fund’s property in trust for the unitholders and supervise the AMC
AMC
The Asset Management Company — the name on the fund
Manages the money, for a fee, under the trustees’ oversight
Custodian
A separate SEBI-registered entity
Physically safeguards the securities and other assets
Follow the money and the design becomes obvious. The sponsor sets it up but does not hold it. The trustees hold it but do not invest it. The AMC invests it but does not hold it. The custodian safeguards it but decides nothing. No single party both controls the decisions and holds the assets, and that separation is the entire point.
The independence requirement makes it real. At least two-thirds of the trustee company’s board must be independent directors who are not associates of the sponsor or the AMC. The trustees appoint the AMC with SEBI’s prior approval, review its net worth quarterly, appoint the custodian, and report to SEBI every six months. They are not a formality; they are the unitholders’ people inside the structure.
A Correction Worth Making
Almost every set of notes says the governing rules are the SEBI (Mutual Funds) Regulations, 1996. They were, for nearly thirty years. The regulations now in force are the SEBI (Mutual Funds) Regulations, 2026, which came into force on 1 April 2026 and have already been amended once, on 7 July 2026.
A second detail that is usually stated wrongly: the trust deed is required to be registered under the Registration Act, 1908. Notes routinely cite the Indian Trusts Act, 1882 instead. The fund is a trust; the deed is registered under the Registration Act. When a regulation names a statute, use the one it names.
What You Actually Own
You do not own the shares the fund buys. You own units, and a unit is a share of the pool.
Net Asset Value (NAV) is the value of everything the scheme holds, minus what it owes, divided by the number of units. It is the price at which you buy and sell, and it is calculated at the end of the day — not live, the way a share price is.
A low NAV is not cheap and a high NAV is not expensive. This is the single most common beginner’s error. ₹10,000 buys the same slice of the same portfolio whether the NAV is ₹10 or ₹500.
Open-ended schemes let you enter and exit any day at NAV. Close-ended schemes have a fixed tenure and are listed on an exchange.
Expense ratio is what the scheme charges you every year for managing the money, taken out of the NAV. You never see a bill; it is simply deducted.
Exit load is a charge for leaving early, meant to discourage churn.
Direct and Regular: the Same Fund at Two Prices
Every scheme is sold in two versions, and the difference is worth real money over a working life.
Regular plan
Direct plan
How you buy it
Through a distributor, broker or agent
Straight from the fund house
Portfolio
Identical
Identical
Fund manager
The same person
The same person
Expense ratio
Higher — it includes the distributor’s commission
Lower
NAV over time
Grows more slowly
Grows faster, for the same investments
Two plans, one portfolio, one manager, two prices. The entire difference is the commission paid to whoever sold it to you. A gap of even a fraction of a per cent a year compounds, over twenty or thirty years, into a sum that is not small. If you are choosing the fund yourself anyway, you are paying for advice you are not receiving.
This is exactly what a disclosure-based regime looks like in practice.SEBI does not forbid the more expensive plan or declare the cheaper one better. It requires both to exist, both to be disclosed, and the difference to be visible — and then leaves the decision to you.
The Kinds of Scheme
Category
What it holds
Who it suits
Equity
Mostly shares
Long horizons; the value moves a lot
Debt
Bonds and other lending instruments
Steadier, lower expected return
Hybrid
A mix of both
Somewhere in between
Solution-oriented
Built for a goal such as retirement or a child’s education
Comes with a lock-in
Index funds and ETFs
Whatever is in an index, in the same proportion
Those who want the market’s return at a low cost
An index fund is worth understanding rather than memorising. It does not try to pick winners. It simply holds every share in an index in the same proportion, so its return is the index’s return minus a small fee. It is the only kind of fund that openly promises to be average — and because its costs are low, average is often enough to beat a large share of the funds that are trying.
ELSS, an equity-linked savings scheme, is the one with a tax angle and a three-year lock-in — the shortest of the common tax-saving options, which is why it is asked about.
SIP, and the One Thing It Does Not Do
A Systematic Investment Plan is simply an instruction to invest a fixed amount on a fixed date every month. It is not a product and not a kind of fund — it is a way of paying into one.
What it genuinely does is remove the decision. Buying the same rupee amount every month means buying more units when the price is low and fewer when it is high, without anyone having to judge which is which. What it does not do is protect you from loss. A falling market falls on a SIP exactly as it falls on a lump sum; the instalments simply arrive at different prices.
Who Watches Whom
Body
What it is
SEBI
The regulator — registers the fund, writes the rules, inspects and penalises
Trustees
The unitholders’ guardians inside the structure, reporting to SEBI twice a year
AMFI
The Association of Mutual Funds in India — an industry body, not a regulator; it sets standards for distributors and runs investor education
Custodian
Holds the assets, separately from the AMC
Registrar and Transfer Agent
Keeps the record of who owns which units
The AMFI distinction is the one examiners use. It is a trade body of the fund houses themselves. It can set codes of conduct and register distributors; it cannot make binding regulations or punish anyone the way SEBI can.India keeps its regulators and its industry associations strictly apart.
Why a Reader Should Care
Money left alone does not stay still.Inflation reduces what a rupee buys every year, so savings that earn less than inflation are shrinking in real terms while the number in the passbook goes up. That is the problem a mutual fund exists to address, and it is why the subject appears in every banking exam.
But notice what the structure does and does not promise.A bank deposit is insured up to a limit; a mutual fund is not insured at all. What the trust structure protects is your ownership, not your returns. If the AMC collapses, the portfolio is still yours. If the portfolio falls, nobody owes you anything — which is precisely what the familiar warning on every advertisement has been saying all along: mutual fund investments are subject to market risks, and the scheme documents are worth reading.
Practice Questions
Q1. A mutual fund in India is constituted as (a) A company (b) A trust (c) A partnership firm (d) A cooperative society Answer: (b) A trust The deed is registered under the Registration Act, 1908, and this legal form is the reason the managing company can never own the money it invests.
Q2. In the structure of a mutual fund, who holds the scheme’s assets for the unitholders? (a) The Asset Management Company (b) The sponsor (c) The trustees (d) AMFI Answer: (c) The trustees The first option manages the money for a fee and the second sets the fund up, but neither of them holds the property, which is the separation the whole design rests on.
Q3. The Net Asset Value of a scheme is (a) The price at which its units last traded on an exchange (b) Assets minus liabilities, divided by the number of units (c) The total money the scheme has collected (d) The return the scheme earned last year Answer: (b) Assets minus liabilities, divided by the number of units It is struck at the end of the day rather than moving continuously, which is one way a unit differs from a share.
Q4. Compared with a regular plan, a direct plan of the same scheme has (a) A different portfolio (b) A different fund manager (c) A lower expense ratio (d) A guaranteed higher return Answer: (c) A lower expense ratio The portfolio and the manager are identical; the only difference is that no distributor commission is built into the charges.
Q5. AMFI is (a) The regulator of mutual funds in India (b) An industry association of mutual funds, not a regulator (c) A department of the Reserve Bank (d) A government-owned custodian Answer: (b) An industry association of mutual funds, not a regulator The actual regulator registers the funds, writes binding rules and imposes penalties, none of which a trade body of the fund houses themselves can do.